Microsoft’s AI Run Rate Hits $37B — Cloud RPO Nearly Doubles
Microsoft FY26 Q3: $82.9B revenue (+18%), AI annual run rate $37B (+123%), Microsoft Cloud $54.5B (+29%), commercial RPO $627B (+99%). The trade is AI monetization at scale with Azure +40% — vs still-opaque AI margin mix and OpenAI-related non-GAAP noise.

The useful number is not total revenue. It is the $37 billion AI annual run rate (+123% YoY) sitting inside a cloud machine whose commercial remaining performance obligation nearly doubled — a rare public scale check on whether frontier AI spend is turning into booked demand.
Microsoft (April 29) reported FY26 Q3 (ended March 31, 2026): total revenue $82.9 billion (+18%, +15% constant currency), operating income $38.4 billion (+20%), net income $31.8 billion (+23% GAAP), diluted EPS $4.27. CEO Satya Nadella: AI business “surpassed an annual revenue run rate of $37 billion, up 123% year-over-year.”
What shipped (earnings primary)#
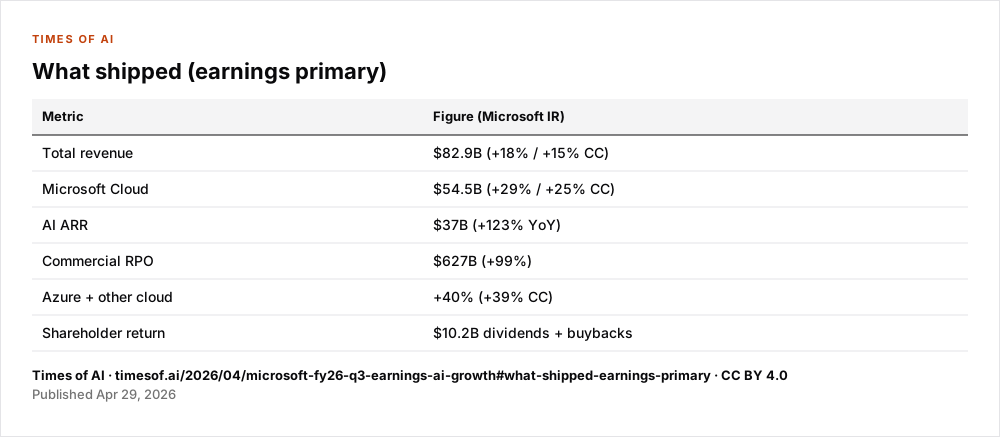
| Metric | Figure (Microsoft IR) |
|---|---|
| Total revenue | $82.9B (+18% / +15% CC) |
| Microsoft Cloud | $54.5B (+29% / +25% CC) |
| AI ARR | $37B (+123% YoY) |
| Commercial RPO | $627B (+99%) |
| Azure + other cloud | +40% (+39% CC) |
| Shareholder return | $10.2B dividends + buybacks |
Segments: Productivity and Business Processes $35.0B (+17%); Intelligent Cloud $34.7B (+30%); More Personal Computing $13.2B (−1%). Inside Productivity: M365 Commercial cloud +19%, Consumer cloud +33%, LinkedIn +12%, Dynamics 365 +22%.
Non-GAAP adjustments primarily reflect impacts from OpenAI investments — according to the company’s disclosure.
Claims vs checks#
Figures are Microsoft Investor Relations primary. The $37B AI run rate is a company-defined aggregate (infrastructure + applications); Microsoft does not publish a fully audited AI P&L or margin stack in the release. Treat ARR growth as a vendor commercialization signal, not independent unit-economics proof. Azure +40% is the infrastructure demand read; RPO +99% is the backlog read.
Limits#
- AI run-rate methodology (what counts as “AI revenue”) is Microsoft-defined.
- OpenAI investment effects blur non-GAAP comparisons.
- MPC decline shows AI lift is uneven across the portfolio.
Sources#
- Microsoft Investor Relations: “Microsoft Cloud and AI Strength Fuels Third Quarter Results” (April 29, 2026). Primary tables and Nadella quote.